
Rudi's View | Jul 30 2026
This story features TECHNOLOGY ONE LIMITED, and other companies.
For more info SHARE ANALYSIS: TNE
The company is included in ASX100, ASX200, ASX300, ALL-ORDS and ALL-TECH
In today's edition:
- TechOne, Still The Number One
- Rio Tinto Opens The August Season
- Picking Winners Pre-August
- Banks: Expensive, Or Maybe Less So?
- How To Value The Wesfarmers Quality?
By Rudi Filapek-Vandyck, Editor
Still The Number One
TechnologyOne ((TNE)) has been a superior performer on the ASX, with a track record that looked so mechanically consistent it had to attract at least one nasty short seller who’d claim the books were carefully manufactured.
Because, you know, there is no such thing as near-perfect; it just had to be fraud.
That GMT Research report caused the share price to come unstuck back in 2020, when a whole lot more was going on, but ultimately the shares would reach new all-time record highs, until the world decided last year the threat of AI disruption to anything software-related was too much to bear.
Post-global carnage, TechnologyOne has been among the first, and the few, to experience a notable re-rating in the sector.
It is hardly a secret this company is, and has been for a long time, one of my personal favourites. Years ago, when questioned after one of my on-stage presentations, “Why do you like this company so much?”, I responded: “Take a look yourself and tell me, what is there not to like?”
Your hardcore fundamentalist value investor will always have the same answer: it is too expensive.
In practice, this company has doubled in size inside five years over the past two decades (you can do the math), and I remain of the view that, following the de-rating from last year’s peak pricing, the odds remain in favour of it doing so again over the coming five years.
Simply put: this truly is one special business. And since when should a Ferrari be priced like a second-hand motorcycle?
This week, I received a message from Chris, an investor who had taken my confidence on board and bought Tech1 shares at around $4. He didn’t sell when they rallied above $40, nor did he buy any extra when they approached $20 earlier this year.
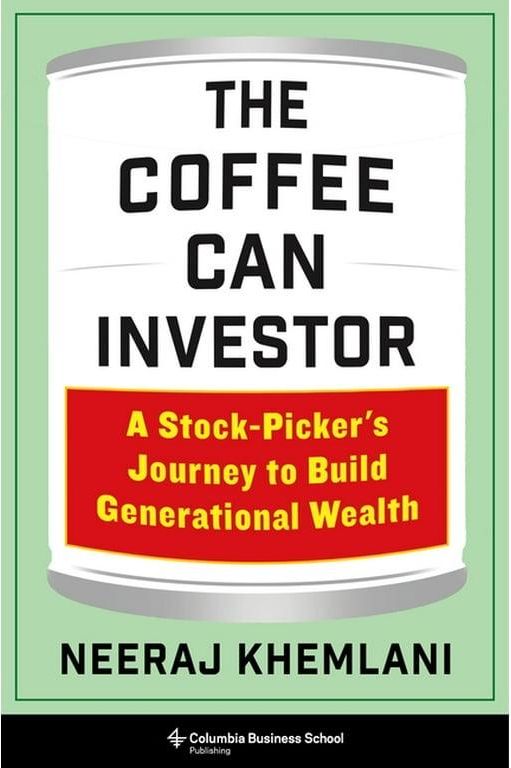
Chris is a happy chappy and, by now, a true TechnologyOne aficionado. He brought along a personal thank-you gift: a copy of The Coffee Can Investor by Neeraj Khemlani, published by Columbia Business School earlier this year.
Of course, I am honoured (that goes without saying), but what makes this book special is that it tells the story of one savvy American investor, Matt Ankrum, and his quest to find the best companies with the best odds of generating significant returns for loyal shareholders who can stay the course.
In easy-to-understand parlance: Ankrum wants to own 10 to 20 future 100-baggers as a gift to his three daughters.
His strategy involved screening 58,000 listed companies worldwide. And after all that work and effort, one ASX-listed company made the cut.
Of course, it is TechnologyOne.
I cannot tell you anything more. I have only just received my copy. But I very much feel obliged to write a review in due course. I must read it first.
Chris’s three largest portfolio holdings are TechnologyOne, Macquarie Group ((MQG)) and Washington H Soul Pattinson ((SOL)).
All three are included in my research on All-Weather Performers and form part of the backbone of the All-Weather Model Portfolio.
Sometimes, from little things, big, gigantic things of beauty grow.
I will be wearing one big smile for the rest of this week, and beyond.
Rio Tinto Opens The August Season
Rio Tinto’s ((RIO)) half-year result marked the start of the local results season in Australia, assuming we casually ignore Newmont Corp ((NEM)) releasing its financials on Friday and James Hardie ((JHX)) pre-releasing its quarterly numbers.
Conclusion number one: the sector is in excellent health, also assisted by robust commodity prices. Analysts are toying with the prospect that August might deliver various positive dividend surprises, with mining companies seated in the front row.
Conclusion number two: Rio is ready to mimic BHP Group in the months ahead. Asset sales are on the agenda, potentially reaping US$5bn or more.
Some analysts believe this pushed up the share price this week, rather than the released financials.
Conclusion number three: Rio Tinto is still short of copper exposure and without a quick fix internally.
Barclays thinks M&A is on the agenda. It is not alone.
Picking Winners Pre-August
Morgan Stanley’s smaller-cap Key Picks for the August results season have now grown to four:
See also:
https://fnarena.com/index.php/2026/07/23/rudis-view-pre-august-picks-in-resources-retail-small-caps/
https://fnarena.com/index.php/2026/07/16/rudis-view-small-cap-favourites-ai-more/
https://fnarena.com/index.php/2026/07/09/rudis-view-julys-stock-pickers-favourites/
https://fnarena.com/index.php/2026/07/02/rudis-view-best-buys-conviction-calls-in-july/
Banks: Expensive, Or Maybe Less So?
Australian banks are always expensive, or so it seems, but it remains tricky to bet against them. This is why the latest sector research by UBS deserves to be highlighted.
UBS’s narrative counters the general view on Aussie banks by identifying institutional banking as the sector’s new growth engine; something the majority of investors have yet to appreciate.
Institutional banking represents a revenue pool of more than $30bn and has delivered cash-profit growth of 11% annually over the past three years, compared with negative -6% for retail banking and 9% for business banking.
Institutional lending is already growing by around 8%-9% annually, supported by infrastructure investment, AI and data centres, defence, supply-chain localisation and the energy transition.
UBS expects this strength to help offset weaker retail banking, particularly as changes to negative gearing are anticipated to reduce mortgage growth by more than two percentage points and place pressure on retail profitability.
The research estimates there may be around $85bn of additional institutional lending not reflected in market expectations.
UBS’s base-case forecasts raise major-bank EPS estimates by up to 2.5% over the next two years; under a stronger-growth scenario, FY28 EPS could exceed consensus by 7.1% for ANZ Bank ((ANZ)), 6.2% for National Australia Bank ((NAB)) and 4.7% for Westpac ((WBC)).
The opportunity is not without constraints. Australian banks generate more than 65% of institutional revenue from net interest income, compared with less than 50% for global peers, making their operations unusually balance-sheet- and capital-intensive.
International banks and specialist boutiques remain stronger in capital-light activities such as advisory and equity capital markets. Capital availability may therefore limit how aggressively the majors can expand unless they recycle loans, securitise exposures or adopt more originate-to-distribute models.
Westpac, National Australia Bank and ANZ Bank are considered best placed. Westpac is the surprise improver, having generated strong recent institutional earnings growth, while National Australia Bank and ANZ Bank possess the largest franchises.
On Thursday morning, UBS upgraded Westpac to Buy from Neutral and raised its target to $45 from $38.80. National Australia Bank remains Buy, with its target rising to $50 from $47.50, while ANZ Bank remains Neutral with a $39 target, up from $35.80.
CommBank ((CBA)), always priced at a sector premium, is Sell-rated because of its valuation, but also because it offers less incremental upside from institutional expansion.
In general terms, UBS finds the Australian banking sector is expensive, trading around two standard deviations above its historical P/E premium to the ASX200, despite an 11% sector ROE remaining below the 12% long-term average.
UBS regards the sector as broadly fairly valued and sector-leading CommBank as fully valued.
Previewing the August results, CommBank’s FY26 result is expected to be broadly in line with consensus. UBS anticipates a three-basis-point second-half margin beat and lower costs, but sees investor mortgage flows and greater back-book competition as the principal risks.
Bendigo & Adelaide Bank ((BEN)) could beat second-half consensus profit by around 5%, supported by a larger loan book. Cost savings from AI and automation provide upside, but possible anti-money-laundering fines and execution risks remain overhangs.
Judo Capital ((JDO)) is expected to miss second-half consensus earnings by around 5%. UBS believes its credit problems are more reflective of internal risk management than broader SME deterioration, but does not expect a re-rating until management rebuilds confidence over several reporting periods.
In summary, UBS anticipates mortgage growth, margins, credit quality and falling property prices will dominate the results, while institutional banking represents the more favourable medium-term offset.
Westpac is scheduled to report its third-quarter update on 10 August, CommBank its FY26 result on 12 August, ANZ Bank its update on 13 August, National Australia Bank on 17 August, Judo Capital its FY26 result on 18 August and Bendigo & Adelaide Bank on 24 August.
For more details on August results outside the banks: https://fnarena.com/index.php/reporting_season/
How To Value The Wesfarmers Quality?
Another stock that is constantly being referred to as “overvalued” or “too expensive” is Wesfarmers ((WES)).
No surprise, then, that RBC Capital initiated coverage this week with a $73 price target and an Underperform rating.
FNArena’s consensus target sits at $79.35, while the shares are trading just below $89 (nearly 11% higher). Only two of the brokers monitored daily have price targets above $80, and only Macquarie’s is in the vicinity of the current price.
The difference in views comes down to the embedded quality of the Bunnings brand and how to value it. Clearly, Macquarie thinks a higher multiple is appropriate.
Other analysts tend to focus more on the risks, since the local housing market is not exactly booming.
RBC Capital’s initiation joins the ex-Macquarie crowd, labelling Bunnings and Kmart best-in-class retail franchises with lengthy growth runways, but assessing the group as overvalued.
Trading at around 22 times forecast FY27 EBIT, Wesfarmers shares are at a 45% premium to the ASX industrials index, compared with an average premium of 18% over the past five years.
Bunnings should benefit from expansion into tools, automotive, workwear and rural markets, although specialist competitors retain advantages in range and expertise. Kmart’s Anko private-label model, low-cost operations and digital expansion should support further market-share gains, while international distribution presents longer-term potential.
Officeworks, Wesfarmers Health and OneDigital offer additional opportunities, but RBC believes stronger execution is required before they become meaningful growth drivers.
RBC’s FY27 EPS forecast sits 2.3% above consensus, largely because of stronger spodumene and lithium hydroxide price assumptions for the Mt Holland mine and Kwinana refinery.
RBC regards this as relatively low-quality upside, given dependence on commodity prices.
Wesfarmers too is proudly held inside the FNArena-Vested Equities All-Weather Model Portfolio.
My research that underpins the Portfolio: https://fnarena.com/index.php/analysis-data/all-weather-stocks/
(Do note that, in line with all my analyses, appearances and presentations, all of the above names and calculations are provided for educational purposes only. Investors should always consult with their licensed investment advisor first, before making any decisions.)
P.S. I – All paying members at FNArena are being reminded they can set an email alert for my Rudi’s View stories. Go to My Alerts (top bar of the website) and tick the box in front of ‘Rudi’s View’. You will receive an email alert every time a new Rudi’s View story has been published on the website.
P.S. II – If you are reading this story through a third party distribution channel and you cannot see charts included, we apologise, but technical limitations are to blame.
FNArena Subscription
A subscription to FNArena (6 or 12 months) comes with an archive of Special Reports (20 since 2006); examples below.


Find out why FNArena subscribers like the service so much: “Your Feedback (Thank You)” – Warning this story contains unashamedly positive feedback on the service provided.
FNArena is proud about its track record and past achievements: Ten Years On
Click to view our Glossary of Financial Terms
CHARTS
For more info SHARE ANALYSIS: ANZ - ANZ GROUP HOLDINGS LIMITED

For more info SHARE ANALYSIS: APE - EAGERS AUTOMOTIVE LIMITED
For more info SHARE ANALYSIS: BEN - BENDIGO & ADELAIDE BANK LIMITED
For more info SHARE ANALYSIS: BRG - BREVILLE GROUP LIMITED
For more info SHARE ANALYSIS: CBA - COMMONWEALTH BANK OF AUSTRALIA
For more info SHARE ANALYSIS: HUB - HUB24 LIMITED
For more info SHARE ANALYSIS: JDO - JUDO CAPITAL HOLDINGS LIMITED
For more info SHARE ANALYSIS: JHX - JAMES HARDIE INDUSTRIES PLC
For more info SHARE ANALYSIS: MQG - MACQUARIE GROUP LIMITED
For more info SHARE ANALYSIS: NAB - NATIONAL AUSTRALIA BANK LIMITED
For more info SHARE ANALYSIS: NEM - NEWMONT CORPORATION REGISTERED
For more info SHARE ANALYSIS: RIO - RIO TINTO LIMITED
For more info SHARE ANALYSIS: SDR - SITEMINDER LIMITED
For more info SHARE ANALYSIS: SOL - WASHINGTON H. SOUL PATTINSON AND COMPANY LIMITED
For more info SHARE ANALYSIS: TNE - TECHNOLOGY ONE LIMITED
For more info SHARE ANALYSIS: WBC - WESTPAC BANKING CORPORATION
For more info SHARE ANALYSIS: WES - WESFARMERS LIMITED