
Rudi's View | Jul 15 2026
This story features TELSTRA GROUP LIMITED, and other companies.
For more info SHARE ANALYSIS: TLS
The company is included in ASX20, ASX50, ASX100, ASX200, ASX300 and ALL-ORDS
SpaceX is looking to invade Australian telecom skies. Should Telstra shareholders be worried?
By Rudi Filapek-Vandyck, Editor
Last week, we let you down, and I am sorry for that.
Usually, its up to Telstra’s ((TLS)) competitors to wear the cloak of humility and address shareholders and/or customers, but this week it was Telstra chief executive officer Vicki Brady’s turn.
Telstra shareholders could be forgiven for dismissing last week’s operational hiccup as simply another storm in a teacup, but public sentiment is shifting in Australia, and outages like the one experienced last week can easily become the next trigger for a more pervasive government response.
After all, telecommunication in today’s modern society is nothing less than critical infrastructure for just about all stakeholders. Not being able to call Triple Zero when disaster strikes is not something any of us wants to confront.
In times of rising populism, and with pressure from One Nation in particular, governments want to be seen as doing the right thing.
The problem for Telstra shareholders is that ideas currently being floated to avoid a repeat, such as mandatory roaming for all mobile phone users, not only translate into additional costs, but could also undermine the telco’s premium market positioning.
Were the latter to occur, questions would be raised about the telco’s valuation, which currently sits at a premium to similar yield providers on the ASX, including two of the big four banks, ANZ Bank ((ANZ)) and Westpac ((WBC)).
A Solidly Growing Payout
At Telstra’s current share price of around $5, the implied forward-looking yield is 4.3%, with consensus forecasting a 21.7c payout next financial year.
This essentially indicates the telco is expected to continue increasing its annual payout to shareholders, in line with the past four years.
Prior to that turnaround, Telstra was the prime example of a badly run company that had become both a dividend trap and a value trap, as illustrated by its inability to maintain dividends and the resulting negative underlying trend in its share price.
Those who gave the new CEO the benefit of the doubt in late 2022 have reaped plenty of rewards.
Shareholders have enjoyed steadily increasing annual dividends since FY22, while Telstra’s share price has simultaneously re-rated from around $2.60 to $5.55 earlier this year.
That turnaround is also evidence of a major shift in investors’ perception of the company, which is now seen as a reliable, solid generator of abundant cash flows that allow for annual increases in shareholder payouts.
The Threat From Satellites
At this point, it’s probably a step too far to fear that the Australian government is preparing to destroy this feel-good investment story, though we live in times when special investigations are launched into supermarkets’ pricing power and potential misdemeanours by petrol station owners.
While banks are always only one step away from the next populist attack, social media and journalists already have data centres in their sights, even though the Australian context and constraints are chalk and cheese compared with those in the US.
But never let facts get in the way of a good storyline, n’est-ce pas?
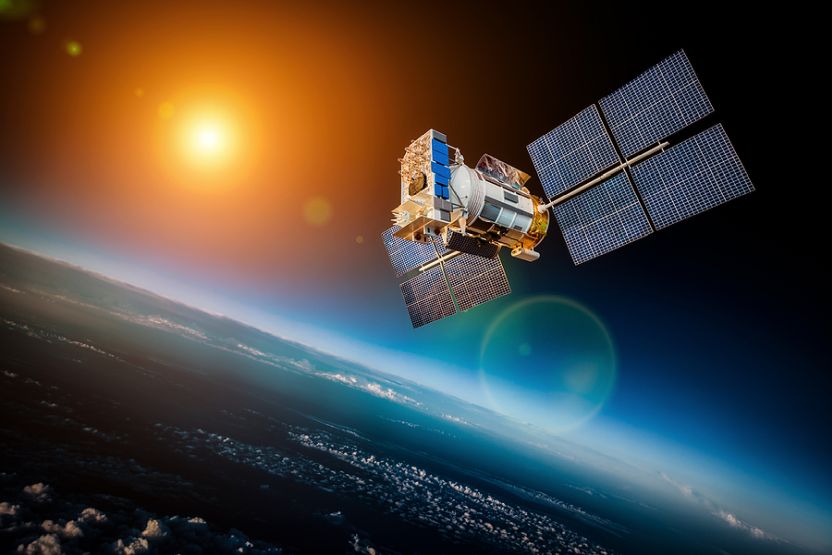
For Telstra, a much bigger threat might stem from the newly Wall Street-listed SpaceX, given its ambition to disrupt the global mobile communications sector.
SpaceX founder Elon Musk has plenty of fans and admirers around the world (myself not included), but even his critics cannot deny he has done a great job of reshaping automobiles and space travel.
I had the opportunity to use his satellite-based internet service a while ago and, no, I was not impressed.
Satellite connections suffer heavily when the sky clouds over. You wouldn’t want to run an online media company such as FNArena on Musk’s network of satellites in earth’s orbit.
I’d probably have no hair left on my head by the end of the first week.
As one in-depth study into SpaceX’s global ambitions put it, while the current technology might be sufficient to provide basic connectivity in remote or underserved regions, the speeds and bandwidth on offer remain well below the average downlink rates provided by terrestrial networks.
This by no means implies Telstra has nothing to fear. Technologies improve. SpaceX intends to launch many more satellites into space.
Meanwhile, the company is forging alliances with terrestrial mobile service providers, such as T-Mobile in the US, and is planning to buy spectrum itself.
A Premium Headache
Rolling out SpaceX’s strategy requires time and lots of spending, and it remains anyone’s guess whether SpaceX will ever be able to make the old business models obsolete.
But that’s not necessarily the crux of this new development. What SpaceX might be able to achieve over time is an erosion of the premium market perception and positioning enjoyed by a domestic market leader such as Telstra.
In simple terms, mobile users in Australia grant Telstra special status because it is perceived as offering the most comprehensive and wide-ranging coverage throughout the country.
This is also supported by the general belief that Telstra’s service is more reliable, with less downtime and fewer outages.
This special status grants the company multiple privileges, including premium pricing for its services. Hence, the board and current management will be keen to sustain that corporate halo.
I’ve personally witnessed the weakness in Telstra’s corporate narrative.
When I travelled to Toowoomba, Queensland, in May to present my insights and financial market observations to local investors, I was forced to use the not-so-great free internet connection that came with the accommodation.
My mobile internet device –specifically purchased from a Telstra shop for travelling purposes– showed hardly any pulse when I switched it on after arriving in Toowoomba.
I tried again on the final day at the local airport, but there was hardly any improvement.
Telstra’s premium image relies on the fact that key competitors Optus and TPG Telecom ((TPG)) cannot offer a more comprehensive service.
One day, perhaps with the help of SpaceXs satellites, this gap may well be closed.
And that, right there, is why there is now an additional question mark on the horizon for management and shareholders.
How To Respond?
The future threat from Musk’s SpaceX has also caught the attention of local sector analysts. Their responses have been markedly different.
UBS takes the view any impact on Telstra’s business is highly speculative at this stage, not least because satellite technology is nowhere near ready to genuinely compete with current terrestrial-based services.
But never say never, and the analysts definitely intend to keep an eye on further developments.
Analysts at Jarden are more worried, which is why they downgraded their rating to Underweight last week and reduced their price target to $4.60.
Jarden fears the emergence of Elon Musk in Australian skies might change investor perceptions, even though the threat itself is still likely to be several years away.
Jarden’s concern is not necessarily wrong. Financial markets are increasingly guided by narratives these days, and we have all witnessed the de-rating of ResMed ((RMD)) shares –supposedly because GLP-1s will eradicate obesity– and of software companies generally because of fears of AI-driven disruption at some point in the future.
The key risk for today’s shareholders is that Telstra shares lose their premium valuation, which would put the share price under pressure without any signs of operational stress.
Were the latter to occur as well, such a double whammy could prove extremely painful.
Investors have plenty of past examples to choose from of companies that lost their premium status and whose shares now trade at much lower levels. One obvious example is the ASX ((ASX)) itself.
One development Telstra shareholders might want to put on their watch list is the federal government’s proposal for a Universal Outdoor Mobile Obligation (UOMO), which is receiving pushback from all major industry participants in Australia.
UOMO promises every Australian access to basic mobile voice and SMS services, no matter where they are in the country.
Currently, mobile networks cover only around 40% of the country’s surface. Adding the remaining 60% is feasible only through satellite technology such as that offered by SpaceX.
For the nerds: were now talking about low-earth-orbit (LEO) satellites.
The current proposal envisages commencement on 1 December 2027, although implementation depends on the commercial readiness of the required technology.
That seems far from a given at this stage.
Telstra shares are held inside the FNArena-Vested Equities All-Weather Model Portfolio and, like UBS, our interest has been piqued.
We intend to follow further developments without panicking at this early stage.
FNArena Subscription
A subscription to FNArena (6 or 12 months) comes with an archive of Special Reports (21 since 2006); examples below.


